The rules of the Bar Council of India (Rule 36) prohibit advocates from soliciting work or advertising in any manner. This website contains general information only, for the convenience and use of visitors seeking it on their own accord, and is not intended to be any form of solicitation or advertising.
By clicking I Agree, you acknowledge that you wish to know more about Ajai Kumar AV and Ajuris Legal on your own accord, that there has been no solicitation of any kind, and that nothing on this website constitutes legal advice or creates a client relationship.
Ajai Kumar AV advises banks, NBFCs, corporates, HNIs and trusts on SARFAESI, insolvency and banking litigation matters, drawing on more than 30 years across the courtroom and banking & corporate legal leadership.
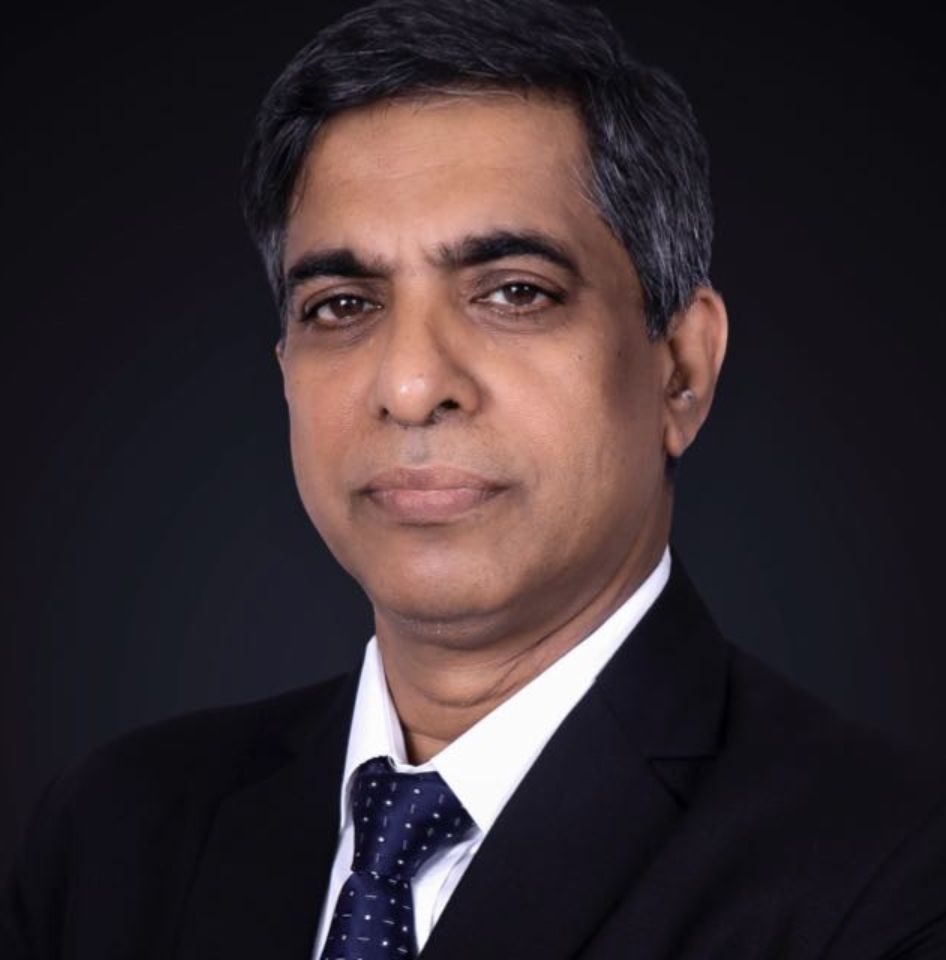
Ajai Kumar AV, Founder of Ajuris Legal, is a practising advocate with over three decades of combined experience spanning legal practice, senior banking legal functions, financial services, recovery, insolvency, regulatory matters, documentation, real estate and litigation.
Having practised as an advocate across commercial and financial matters, and subsequently served in senior legal leadership positions with some of India's leading banks and respected NBFCs, he brings to legal assignments a perspective that combines law with first-hand knowledge of banking business, credit, risk, documentation, recovery and institutional decision-making.
Since retiring from that role, he founded Ajuris Legal to provide practical, legally robust and commercially conscious solutions for complex banking, financial and real estate matters, supported by a Pan-India network of advocates — an integrated approach spanning transaction, advisory and litigation.
Practised as an advocate across commercial and financial matters.
Held senior legal leadership roles with some of India's leading banks and respected NBFCs, overseeing litigation, recovery and regulatory matters at scale.
Independent practice advising banks, financial institutions, businesses and individuals on banking, recovery, insolvency and real estate matters, and conducting related training.
A legal issue concerning a bank or financial institution cannot always be effectively addressed by examining the law in isolation. It may involve the underlying credit transaction, documentation, security, regulatory requirements, internal processes, evidence, recovery strategy and the prospect of litigation.
Having worked within leading financial institutions at senior legal levels, in addition to experience as an advocate, the practice brings an institutional understanding of how banking businesses function, and how legal risks affect business, credit, recovery and management decisions.
Matters handled span advisory, documentation, enforcement, litigation and resolution work. Select an area for the specific matters it covers.
Ongoing retainership arrangements for banks and financial institutions requiring continuous legal support.
Legal opinions on banking, recovery, insolvency and real estate matters requiring specific analysis.
Review of loan, security and transaction documentation to identify enforceability risk.
Strategic oversight and conduct of banking, recovery and related litigation.
Advisory on recovery strategy across the NPA lifecycle, from default through resolution.
Assessment of legal risk in transactions, documentation and stressed accounts.
Structured training for legal, credit and recovery teams on banking law developments.
A combination of independent legal practice and senior in-house banking experience.
An understanding of credit, business processes, risk, documentation, recovery and institutional decision-making.
The ability to examine a matter from transaction structuring through potential litigation.
The focus is not merely on defending disputes but on identifying and mitigating legal risks at an early stage.
Legal advice capable of being implemented within the commercial and operational realities of a financial institution.
The same legal issue can affect business, credit, risk, legal, recovery, compliance and litigation. The practice considers these dimensions together.
General information on processes that come up often. This is educational information, not legal advice on any specific matter — for that, see the contact section below.
A SARFAESI notice (typically under Section 13(2) of the SARFAESI Act) is issued by a bank or financial institution to a borrower whose account has been classified as a non-performing asset, giving 60 days to repay the outstanding dues before the lender can proceed to enforce its security interest. Recipients should have the notice and underlying documentation reviewed promptly, as there are limited timelines within which objections or representations can be made.
If dues remain unpaid after the notice period, the lender may proceed under Section 13(4) to take possession of the secured asset, take over management, or sell/lease the asset to recover dues, generally without court intervention. Borrowers can raise objections with the lender, and if aggrieved by enforcement measures, can approach the Debt Recovery Tribunal (DRT) under Section 17.
SARFAESI is a self-enforcement mechanism allowing banks and financial institutions to recover secured debts without first approaching a court. The Debt Recovery Tribunal (DRT), by contrast, is a specialised tribunal that adjudicates recovery suits filed by banks under the RDB Act, and also hears appeals and challenges against SARFAESI enforcement action under Section 17.
Section 7 of the Insolvency and Bankruptcy Code allows a financial creditor to initiate the Corporate Insolvency Resolution Process against a corporate debtor in default. Once admitted by the NCLT, a moratorium applies, a resolution professional takes over management, and creditors participate through the Committee of Creditors to decide the debtor's resolution or liquidation.
A Non-Performing Asset (NPA) is a loan or advance where interest or principal repayment has remained overdue for a period specified by RBI norms, generally 90 days. Classification triggers specific regulatory and provisioning consequences for the lender, and often precedes recovery action such as SARFAESI or IBC proceedings.
The Real Estate (Regulation and Development) Act, 2016 (RERA) regulates real estate projects and protects allottees through mandatory project registration, disclosure requirements, and remedies for delayed possession, including refund with interest or compensation. Complaints are filed before the state Real Estate Regulatory Authority, with appeals lying before the Appellate Tribunal.
Disputes involving Maharashtra co-operative housing societies, including redevelopment, membership and governance issues, are generally addressed through the Maharashtra Co-operative Societies Act, society bye-laws, and where applicable, the Co-operative Court or Deputy Registrar, alongside the contractual and regulatory framework governing the specific redevelopment agreement.
Both. Ajuris Legal advises institutional clients — banks, NBFCs and financial institutions — as well as individual clients, including businesses, developers, property owners, allottees and individuals facing banking disputes, recovery proceedings or real estate matters.
A legal retainership is an ongoing engagement, typically used by banks and financial institutions, under which Ajuris Legal provides continuous legal support across recovery, litigation, documentation and regulatory matters rather than being engaged on a matter-by-matter basis. Scope and terms are agreed individually based on institutional requirements.
Whether the matter concerns a banking transaction, stressed account, NPA, SARFAESI proceeding, IBC matter, banking documentation, regulatory issue, RERA dispute, redevelopment matter, co-operative housing society issue or litigation, the first step is a clear assessment of the legal and factual position.